Sunday, 8 October 2017
明年油价或涨至100 美元
當原油價格去年初崩跌至每桶27美元時,多數行業高管稱,之前每桶100美元的油價已成絕響。
時間過了近2年後,隨著全球原油過剩局面出現緩解跡象,石油期權市場押注每桶100美元的合約交投活動出現大增,暗示部份油市多頭,正在押注油價可能在明年的這個時候,來到這個價位附近。
原油價格已觸及2015年以來最高,而在9月最后一周挑戰每桶60美元失敗後,漲破此一關卡的機率似乎比較渺茫。但這並未阻止部份投機客逢低買進2018年12月行權價為每桶100美元的買權。
2018年12月行權價每桶100美元的買權未平倉合約,在一周之內暴增2倍,至逾3萬宗,接近今年12月交投最熱絡的行權價60美元買權。2018年12月原油買權將於明年10月到期。
儘管單看該數據,還不能暗示投資者是否已買入或賣出這些合約,但這確實說明,油價在略超一年後接近100美元的前景,並不像一些較樂觀的多頭所預想的那麼遙不可及。而且,這是目前對2018年全年最高的行權價。
即便100美元短期還不可能達到,但未來幾個月看漲的理據明顯增加。明年需求勢必將首次超過每日1億桶的關口,同時石油輸出國組織( OPEC)供應,可能至少在明年的部份時間仍受到抑制。行權價每桶90美元的12月買權,已吸引到大量交易員和投資者的興致。
3年來油價持續低迷,促使企業將開採預算削減數以10億計美元,意味著正在進行的新項目也相當少。
羅賓生( Richard Robinson)表示,「我們極其確信,未來3到5年,油市將是一個很好的投資領域。」
「歷史上看,支出不足的表現疲弱階段,正如我們過去5至8年所看到的那樣,接下來會是長度相同的表現出色階段。」他倒是沒有預言,油價會達到100美元。
「支出缺乏通常會自食其果。由於庫存不久將達到平衡,市場心理會隨之發生變化,而投資者提出的問題也將改變。根據目前的勢頭,我們預計,隨著油價走高,將會出現重大機遇。」
儘管如此,在最近的《路透》月度油市調查中,最樂觀的預測也只是油價到2020年,將達到每桶80美元。這種謹慎心態,部份緣於OPEC內外的生產商,可能趁油價大漲之機來提高產量,尤其是美國頁岩油生產商。
OPEC與包括俄羅斯在內的11個夥伴國,已承諾於今年1月至明年3月每日減產180萬桶,希望藉此迫使原油供應過剩能逐漸枯竭,從而推升油價。不過目前需求正在「攀升」,明年可能增至每日1億桶。
2014年,在油價徘徊於每桶110美元左右4年之後,多數分析師當時說,油價永遠不會回到100美元以下,而現在大家卻又說,油價永遠回不到當初的高價了。即原油生產成本,已結構性下降,而且電動車將對需求,產生足夠大的衝擊。
OPEC達成減產協議的最初6個月,全球原油庫存幾乎沒有變化,但如今庫存水平看來終於下降,而且實貨市場也顯露出至少3年來未曾見過的強勁態勢。實貨市場經常是期貨市場狀況的晴雨表。

Sunday, 1 October 2017
买股的禁忌
炒股大忌:
1. 看到新闻,听到消息,就马上买入
2. 把所有资金只买入一只股
3. 一次过买完所有的资金 (无论是买多少只股)
4. 买入太多只股
5. 股价大跌,尝试捞底
6. 只看基本面就满怀信心大手买入
7. 大手买入一只上涨股,但是不了解它的基本面
8. 看到基本面差,就怕死不敢买入正在上涨的股,你可能会错过地表最强最有力反弹的股
9. 买入一只股却没有起,看到另一只股起,就快快换货,不断杀进杀出,没有耐心
10. 买入一只股后一直跌却不舍得或者不懂得如何止损
以上有些是关于资金分配,有些是关于买卖操作,有些是关于研究的方法,有些是与心态有关,不能单独只看某一项,必须全盘关注,别忘了,往往是一子错,满盘皆输,切记切记
请大家不吝分享炒股经验和如何避免亏损,谢谢 :)
Monday, 18 September 2017
Tuesday, 12 September 2017
炒股
炒股最好放慢一点脚步
天天赚10%是不会发达的,年年赚30%才会致富,为什么呢?
每天都有股票上涨超过10%,前提是必须在它上涨之前买入,而且是每一天。 但这还是其次,最重要的是,如果有$300k,每天要在低价位 match 到$300k的单,这就不容易咯
要在股市赚大钱,最好退而求其次,不要去追求天天找到暴涨股,每个周末习惯性的过滤股票,把上升股放进 watchlist,也加入一些平行了蛮久而开始有较高成交量出现的股
买股一定要买处于上升趋势的股,不要买当天就爆升20%的股,短期内涨得太快,未必能持久,可能不过三几天就暴跌了,当然它也可能继续往上冲
上升股一般上都会跟着公司业绩或者好消息公布的时间表同步进行,大马内幕信息管制很糟糕,所以才会出现大军未动,粮草先行的情形,当一只股的股价在没有任何消息的情况下上升,就要紧紧跟踪和布局进场
在一波上涨行情当中,基本上大鳄都会计划最少30-100%的盈利,所以我们可以从这里预测一只股可以上涨多少,只要大鳄没有套利退场,这股就可以永不停滞的往上爬,有很多例子显示,上涨超过200-500%的股,比比皆是
所以,买到暴涨股未必会赚大钱,但是,买到处于上升趋势初期的股,顺势而为,这才是炒股致富之道矣
以下的例子只是作为参考而已,一些股的上升趋势已经确定,一些股才刚刚在低位出现大成交量,上升趋势还没有成形,大家要有耐心和花一点时间做功课,了解公司的背景和经济大环境,炒股赚钱并不太难,请记得古人云:欲速则不达,是有一定的道理的
Monday, 11 September 2017
Buy in Experience After Awaiting
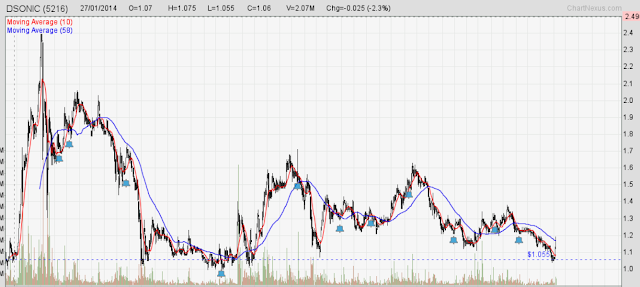
DSONIC
SENERGY

Comment:
When monitor the stock for sometimes, what is the best timing to buy in the stock?
1) When the stock hit the previous low level possible to buy first batch of the stock to try in, if the stock keep uptrend for 5% can buy in another batch as well.

SENERGY

Comment:
When monitor the stock for sometimes, what is the best timing to buy in the stock?
1) When the stock hit the previous low level possible to buy first batch of the stock to try in, if the stock keep uptrend for 5% can buy in another batch as well.
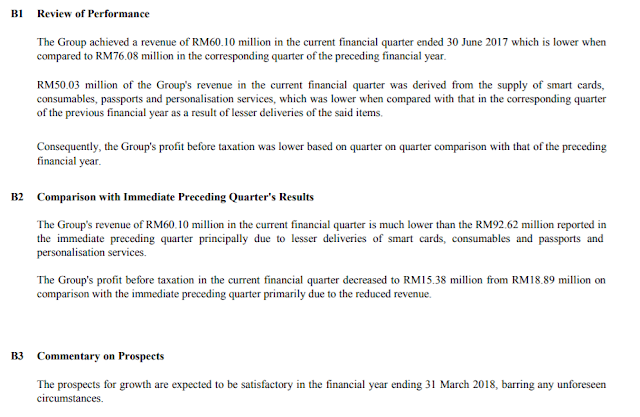
DSONIC(5216)
Company quarterly revenue

Equity , Asset & Liabilities

Cash Flow


Review of Performance
Borrowings


Equity , Asset & Liabilities

Cash Flow

Segment Profit


Borrowings

Thursday, 24 August 2017
JAYA TIASA HOLDINGS BHD
JTIASA
Financial result for the quarter ended 30 June 2017

Profit before taxation for this period is due to the other expenses of 66million on impairment loss of RM62.3 million on goodwill and also the RM3.7 million on the carrying value of its plant and machinery used in the wood production activities was recognized.
Actual profit if exclude the RM66 million impairment is actually RM-43,870 - RM66,084 = RM 22,214

Asset

The borrowings of the JTIASA si quite high which is 483million for current liabilities and also 591 million for the non current liabilities. This is also not a sign as the finance cost for the company is 11,413 million for this quarter which is about 4.7% from the total revenue.
Segment Results YoY

Overall segment like Logs, Wood processing both of the revenue & profit keep dropping but exception for the Oil Palm which recorded an increase in profit . Overall profit recorded are lower than last years.
Segment Results QoQ

Segment Results Current Vs Previous Quarter

Commentary on Prospects

Look like the management is not very optimistic on the further company prospect.
Borrowings

Borrowing for the company is too high.
International Oil Palm Price

Financial result for the quarter ended 30 June 2017

Profit before taxation for this period is due to the other expenses of 66million on impairment loss of RM62.3 million on goodwill and also the RM3.7 million on the carrying value of its plant and machinery used in the wood production activities was recognized.
Actual profit if exclude the RM66 million impairment is actually RM-43,870 - RM66,084 = RM 22,214

Asset

Segment Results YoY

Overall segment like Logs, Wood processing both of the revenue & profit keep dropping but exception for the Oil Palm which recorded an increase in profit . Overall profit recorded are lower than last years.
Segment Results QoQ

Segment Results Current Vs Previous Quarter

Commentary on Prospects

Look like the management is not very optimistic on the further company prospect.
Borrowings

Borrowing for the company is too high.
International Oil Palm Price

Subscribe to:
Posts (Atom)